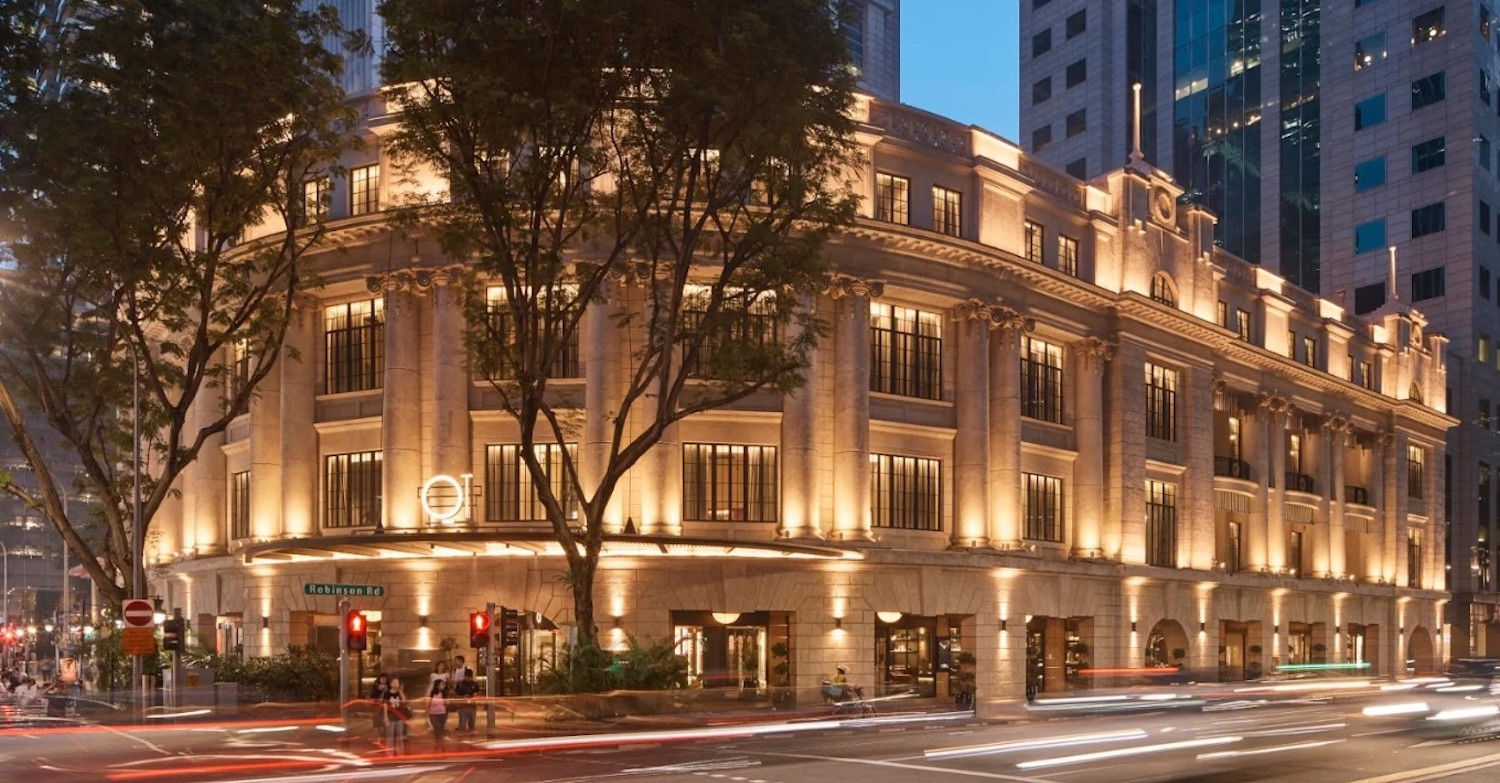
CapitaLand’s proposed purchase is about A$436,000 per room, 26% above the reported Hotel Indigo price on the same street. The fund’s 8% distribution target puts the focus on what the rebranded hotel can earn.
A Mirae Asset-managed fund has agreed to buy the Gangnam office at a reported price of at least KRW200 billion, 14% above Hana’s 2025 purchase. The tower was 53% let at midyear.
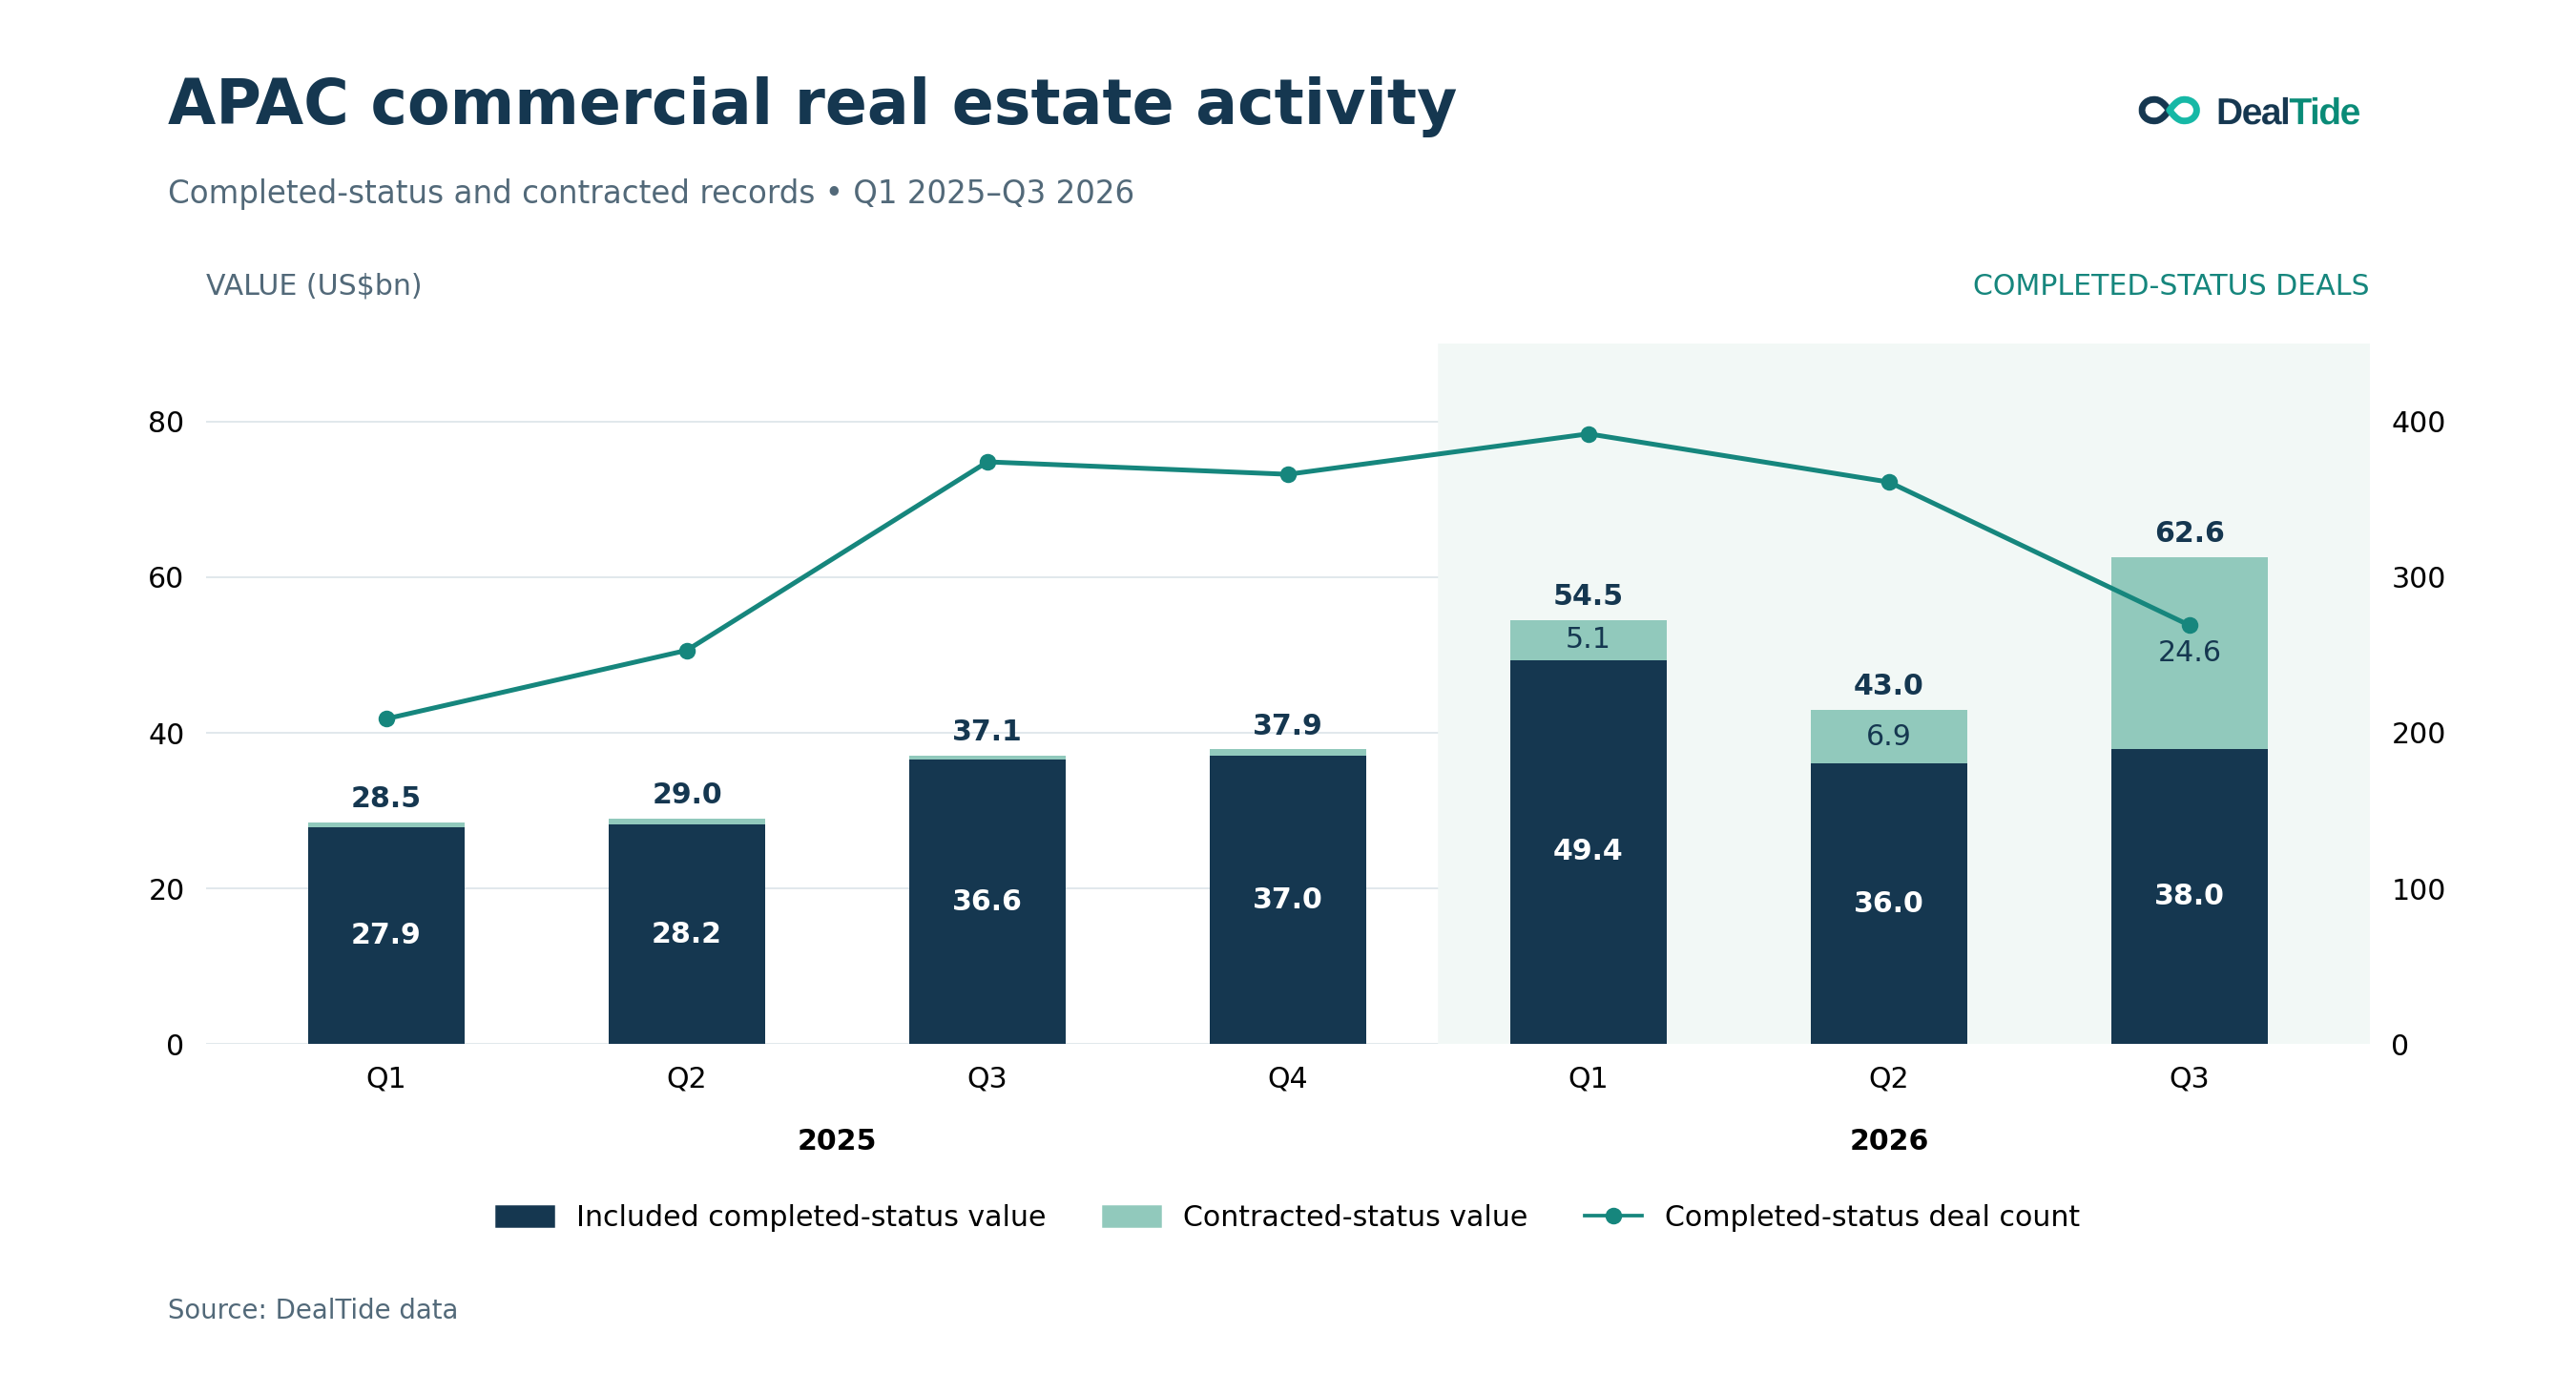
APAC data centre deal value rose to US$12.2 billion in the first nine months of 2026, from US$3.2 billion a year earlier. Without the STT GDC and WinTriX China sales, completed deal value fell 3% to US$3.1 billion, and direct asset purchases were flat at US$2.06 billion.
LANDMARK Orchard is Hongkong Land’s first use of the name outside Hong Kong. Marina One’s illustrative S$2.85bn equity requirement shows the scale of its next funding decision.
At about S$10 million per building and S$2,778 per sq ft, the reported portfolio sits below nearby sale campaigns. Its shorter leases put the focus on what 8M can earn from a much larger neighbourhood cluster.
The Clarke Quay hotel costs less per room than two recent nearby deals. Its projected 4.8% stabilised yield requires about S$130 of property income per available room-night, while unitholders fund the build-up.
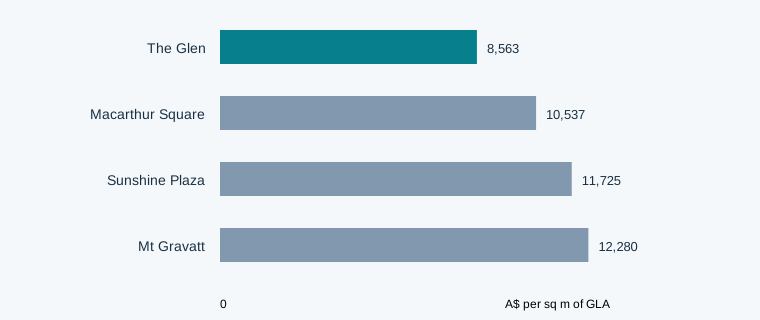
At about A$4,445 per square metre, Mainfreight’s facility is priced between two Sydney comparisons. Its appeal includes an 8.5-hectare site and a tenant that has built its operation around it.
TJ Media’s reported KRW40bn commitment may have helped close a delayed KRW119.5bn office sale. At roughly KRW3.4m per sq m, the western Seoul offices trade well below selected CBD deals—but their income still has to support the price.
Four buildings, 313 rooms and an illustrative ¥417 million of annual gross rent: the shift into a core-plus fund raises the question of how the same manager priced both sides.
About A$1.7 billion changed hands in the first nine months of 2026. Recent pub sales reveal the difference between buying rent and buying an operating business.
From NEX and One Raffles Place to IOI’s office portfolio, a growing pipeline of major properties is testing the depth of investor demand. But how many of these deals will cross the line?
The reported A$200 million price follows a A$13 million refurbishment. The offices offer leasing upside, while Adidas generates about three times the building-wide gross income per square metre.
The Widjaja family buyer is considering more than S$3,600 per sq ft—well above three other Singapore office deals. Freehold tenure and a hotel-conversion option help explain the premium as year-end dealmaking gathers pace.
The reported price is close to LaSalle’s 2024 Anseong entry, while a 284,220 sq m Musinsa project adds a tenant question to the rent-reset opportunity.
The A$50m purchase of 26 Flinders Street delivers a refurbished building and existing rent. Keeping that income growing becomes more important after Australia’s latest rate increase.
Newer towers are capturing much of the financial sector's leasing demand. Falling vacancy and rising rents mark a recovery, but older buildings still face the task of winning replacement tenants.
DHLT plans to replace a largely empty Sendai warehouse with a fully leased Hiroshima property. Its sponsor’s willingness to pay above valuation makes the switch possible.
The revised A$5.45 cash proposal tops AVID by 10 cents, with Discovery Parks and LDR Capital lined up for two businesses that earned A$74.5m last year.
BlackRock is reportedly negotiating a RMB634m sale of Trinity Place. Its office rents help explain why the prospective buyer is considering apartments.
The additional 50% comes at a lower property valuation, but attributable duty and fees take its cost above March’s price benchmark. The advertised 3.2% distribution uplift also depends on the earnings period and financing.
Overseas institutions, REITs and developers are behind most of this year’s deals. DealTide looks at who bought, the yields they accepted, and the deals that could push the total past S$50bn.
Planned additional borrowing equals about 82% of the S$600m property value. Last year’s gross income was just 3.8% of that value, putting the loan terms and the strata exit at the centre of the deal.
The KRW215bn purchase puts the two business hotels close to voco Myeongdong’s price per room. Repositioning has to lift earnings enough to cover both the entry price and the cost of the work.
ParkCity-linked investors are buying the 1,219-room complex for HK$2.7bn. Occupancy is close to 85%, but the price covers only 60% of the reported loan balance.
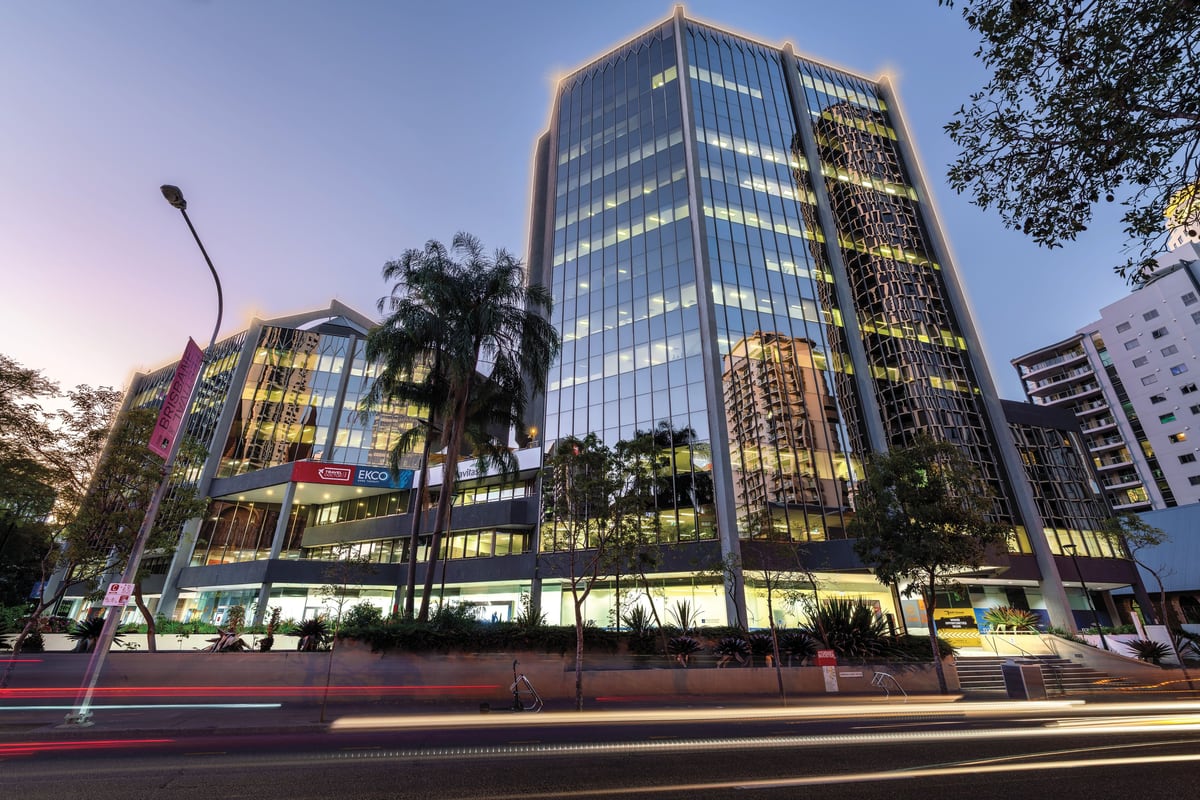
Alceon’s parking adjustment puts the Brisbane offices below A$4,000 per sq m, with around 90% leased. The 11% fully leased yield depends on the coming rent resets and what it costs to upgrade the towers.
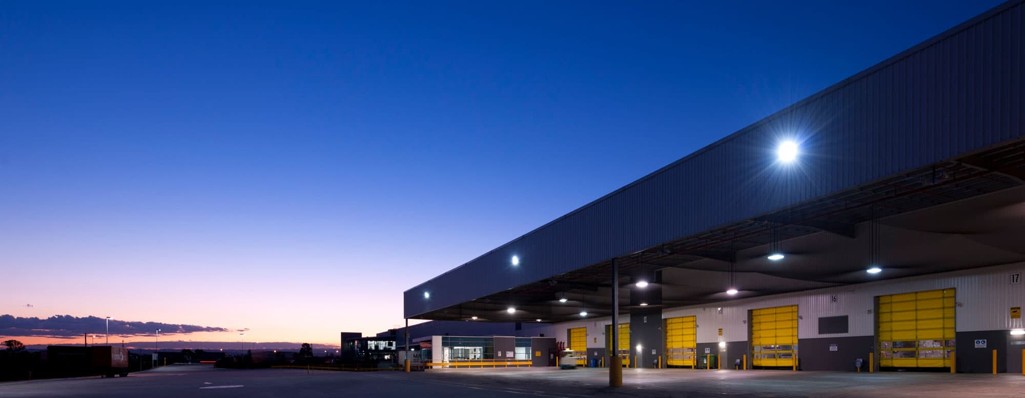
The A$44m sale turns a logistics operator’s property into leased infrastructure. For the buyer, the hardstand and rail access matter alongside the warehouse.
A S$626.2m property interest comes with a 4.3% initial yield supported by the seller. The test is whether leasing can replace that support before it expires.
The Sydney and Brisbane portfolio combines a largely occupied tower with offices needing new tenants. Deferred consideration gives the buyers 30 months to pay the balance.
A hotel REIT sells at a 1.5% yield on historical income and buys at a 3.4% forecast yield. International funds hand assets to new owners. Japan’s latest deals reveal how much investors will pay for the next stage of growth.
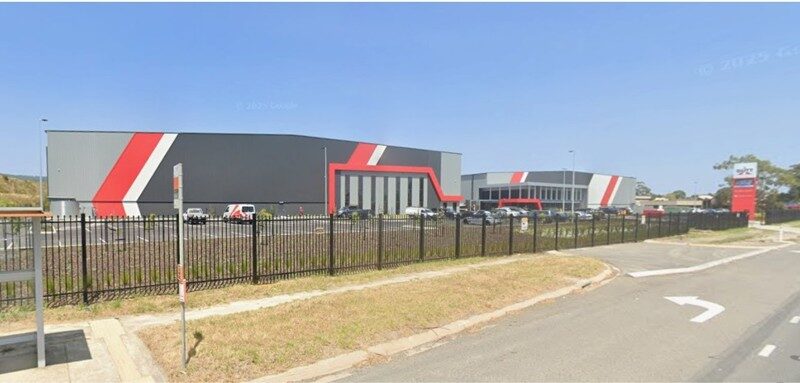
Fife bought the Kilsyth site for A$17m in 2021, developed a logistics headquarters now occupied by DUTT Transport, and sold for more than three times the entry price.
DealTide records 58% growth in first-half warehouse investment, but only four more transactions. Goodman’s Australian partnership acquisition accounts for 85% of the increase.
Invesco’s student-housing launch adds to a wave of institutional investment around Seoul. The opportunity rests on monthly rents, local operators and the ability to build homes tenants can afford.
Forza spent a decade collecting rent and improving the building. Daiken is adding Queensland property income with the option of a much larger development later.
SC Capital’s investment brings foreign equity into a project backed by Korean banks, government-linked capital and an anchor tenant. The funding combines secured power, a tenant commitment and a builder responsible for completion.
Deals are back, and DealTide’s figures show more transactions at a smaller average size. The recovery in rents and financing is less even: buyers are finding different reasons to act.
Receiver-led disposals in Yuen Long and steep losses on city shops are creating new entry prices, but the rent behind each deal matters more than the headline discount.
Crystal Bridge Tower 5 adds a new price point beside PDD’s DBS Bank Tower purchase and Lalamove’s neighbouring acquisition, while occupier demand follows a different logic from rental investment.
Recent transactions in DealTide's records span operator platforms, contracted rental income and development sites—and the headline prices measure different things.
The REIT is selling smaller apartments at ¥1.21m per leasable sq m and buying larger 2023-built homes at ¥1.52m, using the ¥2.15bn sale proceeds to help fund the purchases.
Garden City’s reported A$13.7m price implies about A$188,000–A$190,000 per room. Recent ACT sales offer context, although room counts and deal structures limit direct comparison.
A 7.74% quoted yield comes with roughly 20% vacancy and a two-year vendor rental guarantee, putting leasing execution at the centre of the acquisition.
The completed sale is approximately 6% above an implied June valuation of S$260m; each additional S$1m of annual net income would add about 0.36 percentage points to income yield at the purchase price.
The Empire in Bangkok represents 51.8% of the proposed minimum seed value, making a five-property REIT materially concentrated in one commercial asset.
Reported consideration above JPY38bn compares with a JPY30bn purchase, while a possible short-stay strategy gives the buyer a different operating case.
The 334,000 sq m Anseong development has a reported KRW600bn budget, putting its delivery cost at about KRW1.8m per sq m before the partners demonstrate leasing.